Insurance Sales Resume Examples
Name your years in insurance sales and the lines you write: personal auto, home, life, health, commercial, or a mix. State the channel you sell through, such as captive agency, independent brokerage, call center, or…
Every resume example is written and reviewed by our team of Certified Professional Resume Writers to ensure top-quality content and formatting.
Your claim volume, settlement accuracy, and cycle time tell a story numbers can back up. A strong claims adjuster resume leads with those metrics. In states like Florida and Oklahoma, listing your state adjuster license also signals you are ready to start.
Claims managers and insurance carrier recruiters look for proof you can investigate losses and close files on time. Credentials like the AIC or CPCU from The Institutes strengthen a mid-career or senior resume. The examples below show how to present these details in a format that works. To compare layouts before you start, browse our resume templates.
Claims managers scan the summary for claim volume handled and line of business first. Where your state requires an adjuster license, list it in the credentials block to stay competitive.
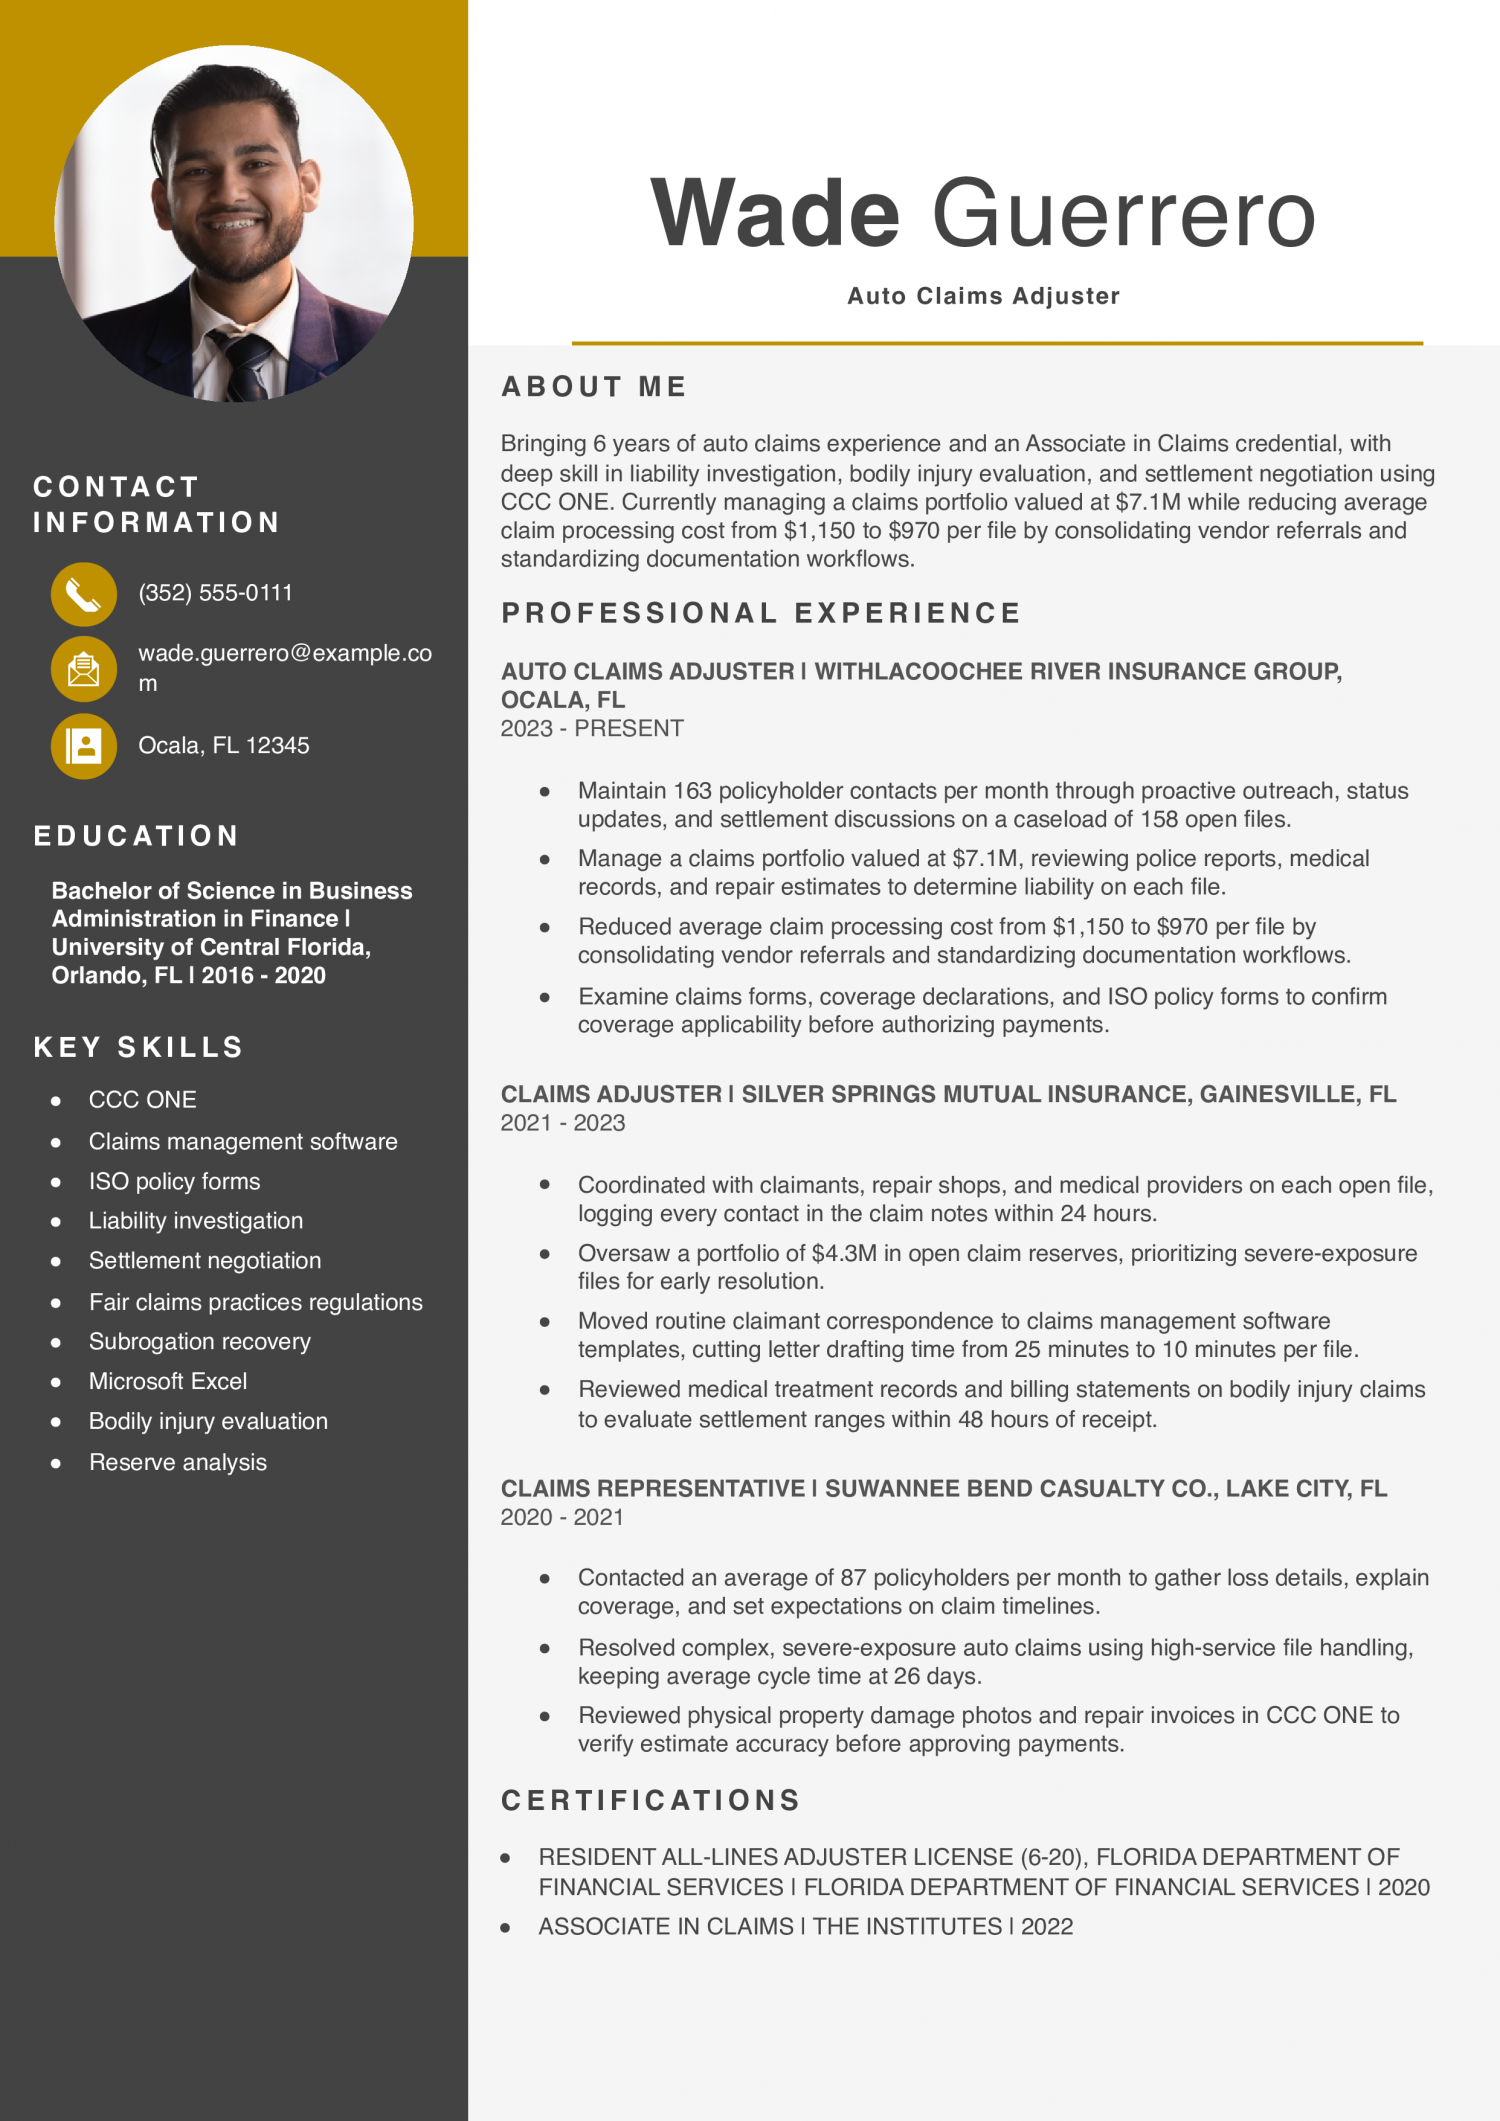
Pick this resume if you are a mid-level auto claims adjuster with about six years of experience and a Resident All-Lines Adjuster License. Copy the way it traces per-file cost reductions across roles to demonstrate growing efficiency.
Per-file cost drops are clear when both the old and new amounts appear together. A claims manager can see the savings per file and multiply them across the caseload. Show your cost reduction the same way: the starting cost, the ending cost, and the change you made.
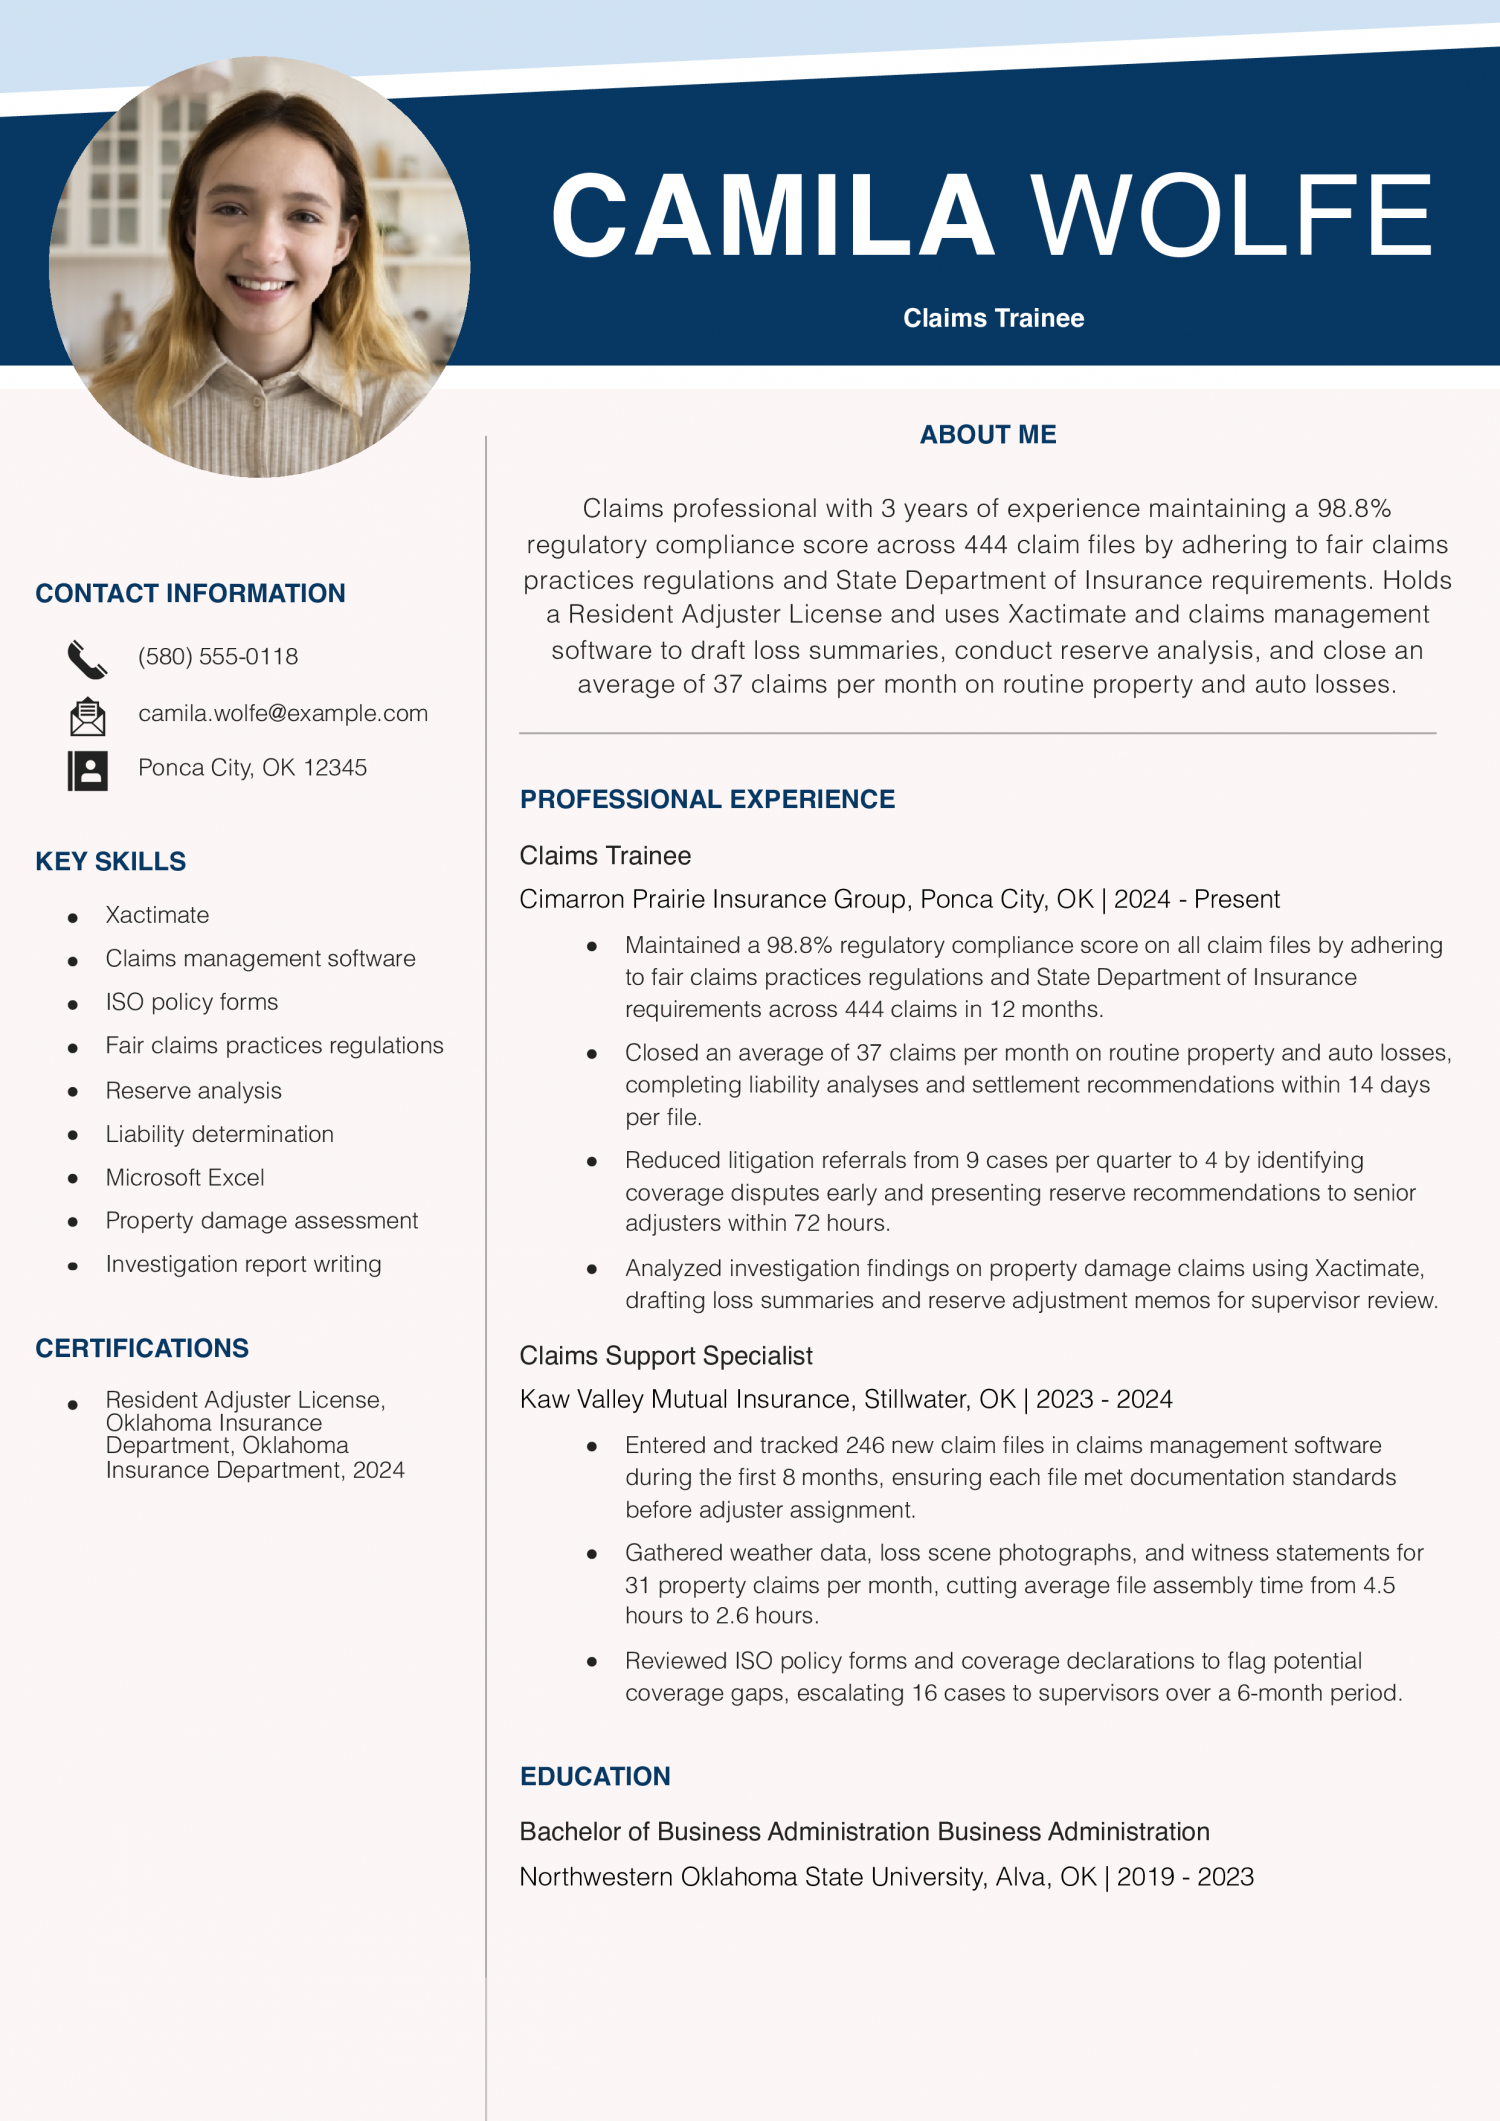
Start with this resume if you are an entry-level claims trainee building your first year of adjuster experience after a support role. Follow how it tracks litigation referral reductions to show early dispute-resolution instinct.
The resume names liability analyses and settlement recommendations completed within a set number of days per file. A supervisor sees how fast the work moves from open to closed. Attach a turnaround window to your own file work so reviewers can judge your speed.
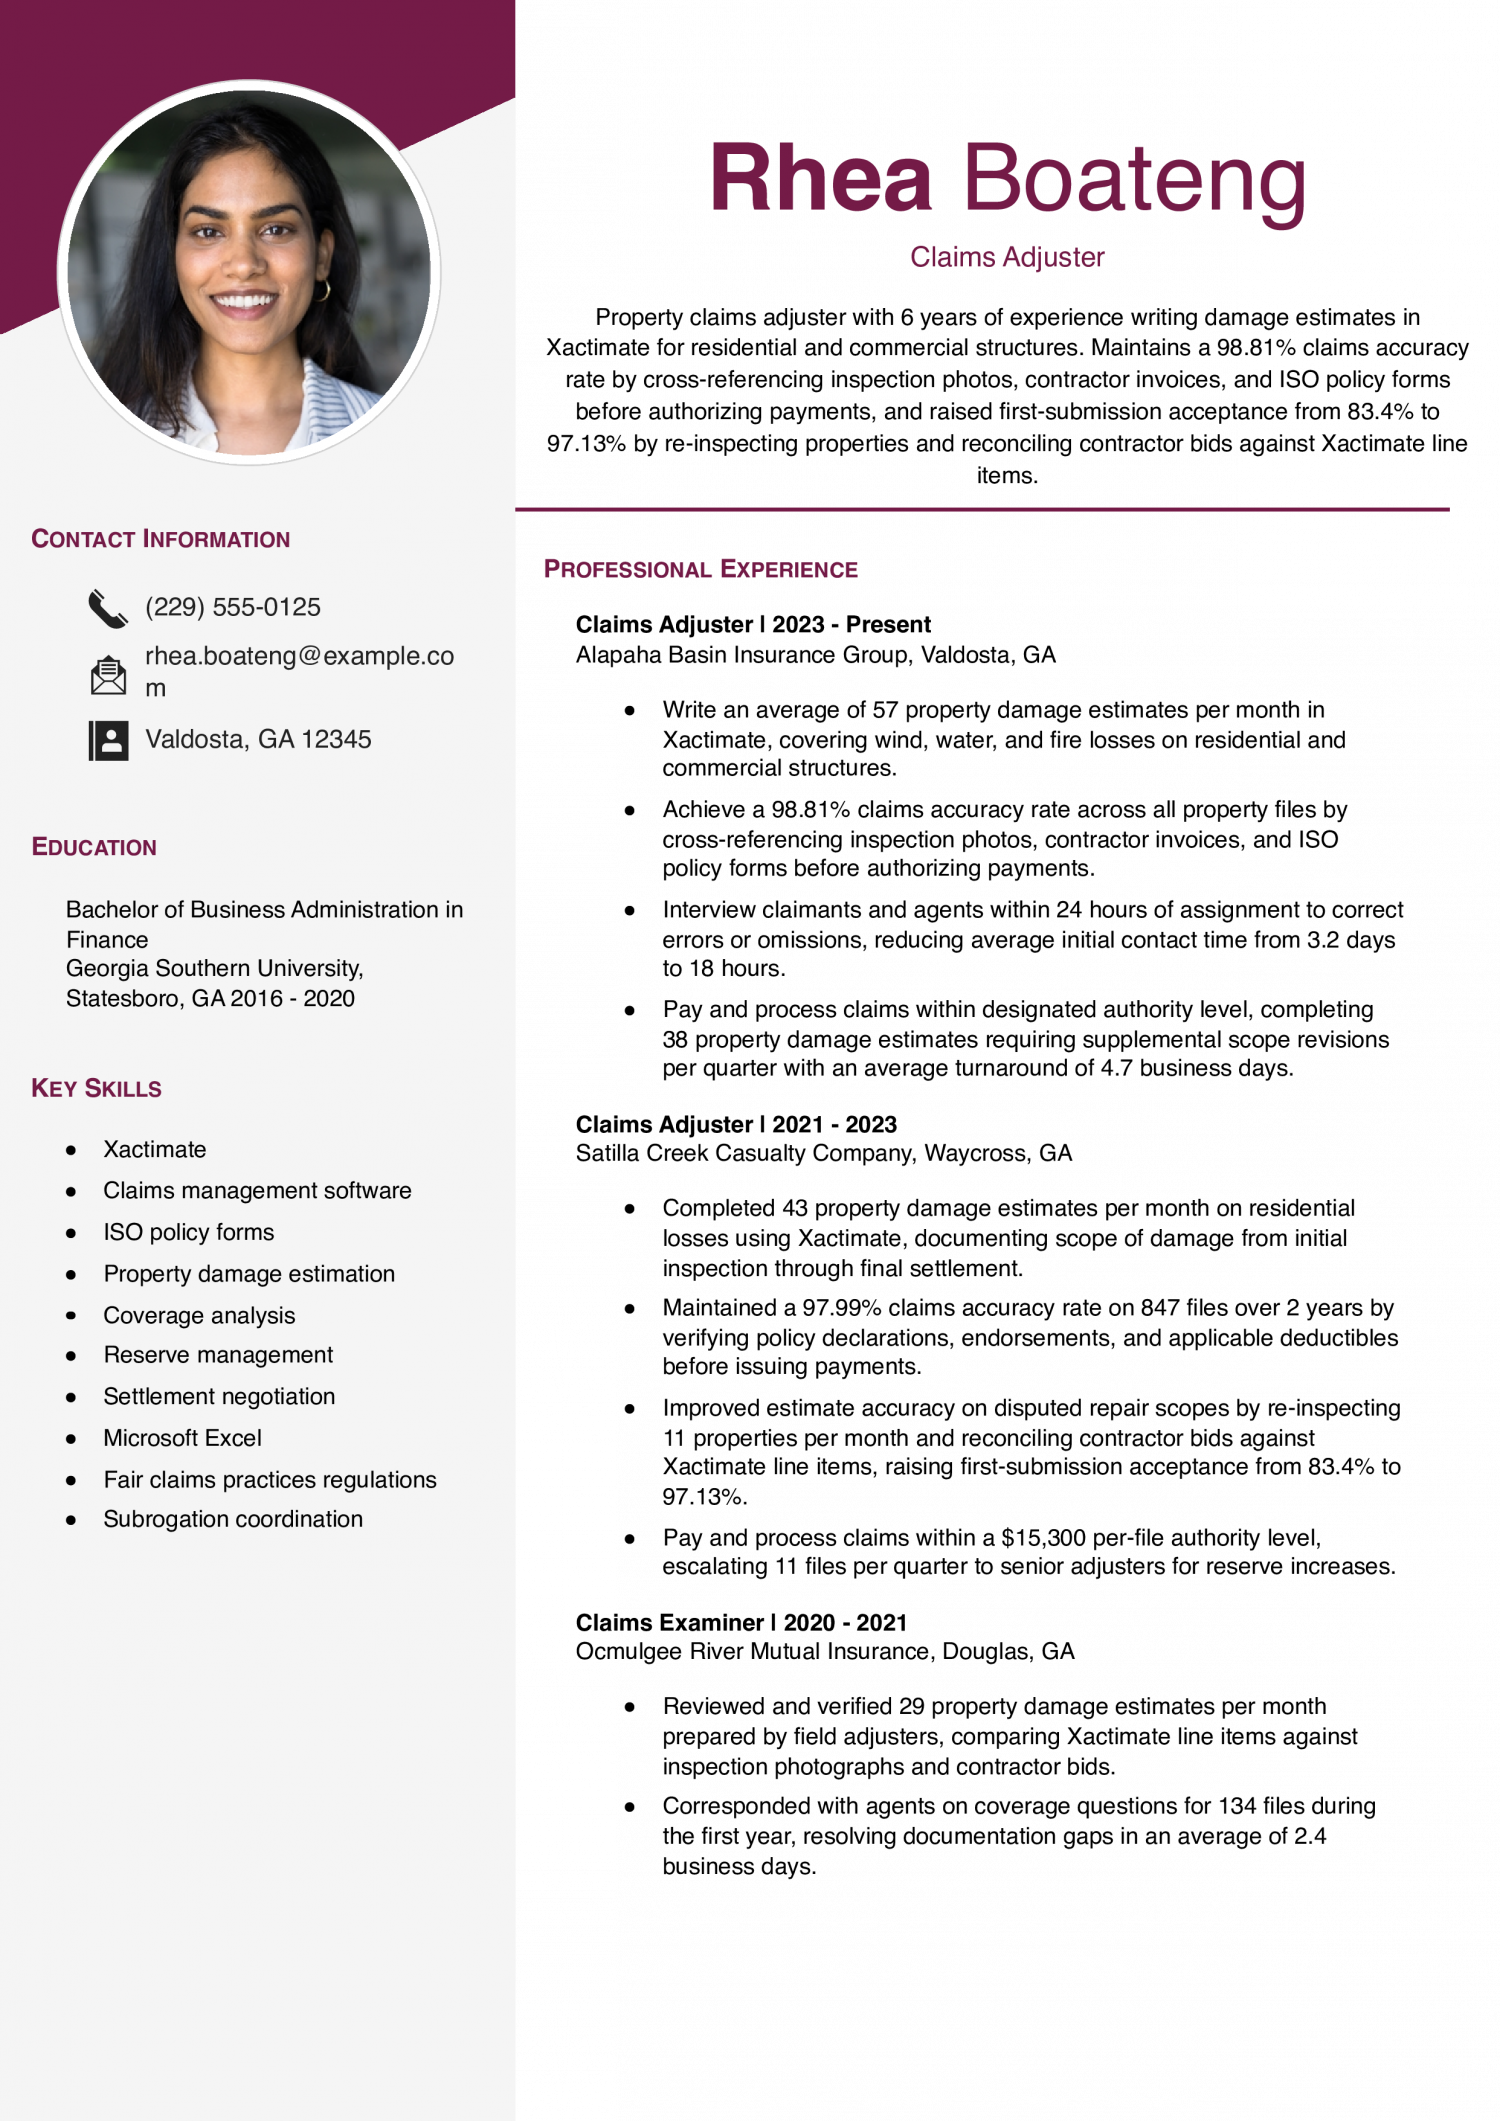
Try this resume if you are a mid-level property claims adjuster with about six years of experience handling wind, water, and fire losses. Raise your accuracy narrative by showing a climbing claims accuracy rate from one employer to the next.
First-submission acceptance jumped because the process behind each claim was tightened. A claims manager can measure the improvement when the starting rate and the ending rate appear together. If you refined a process, show where the rate was and where it went.
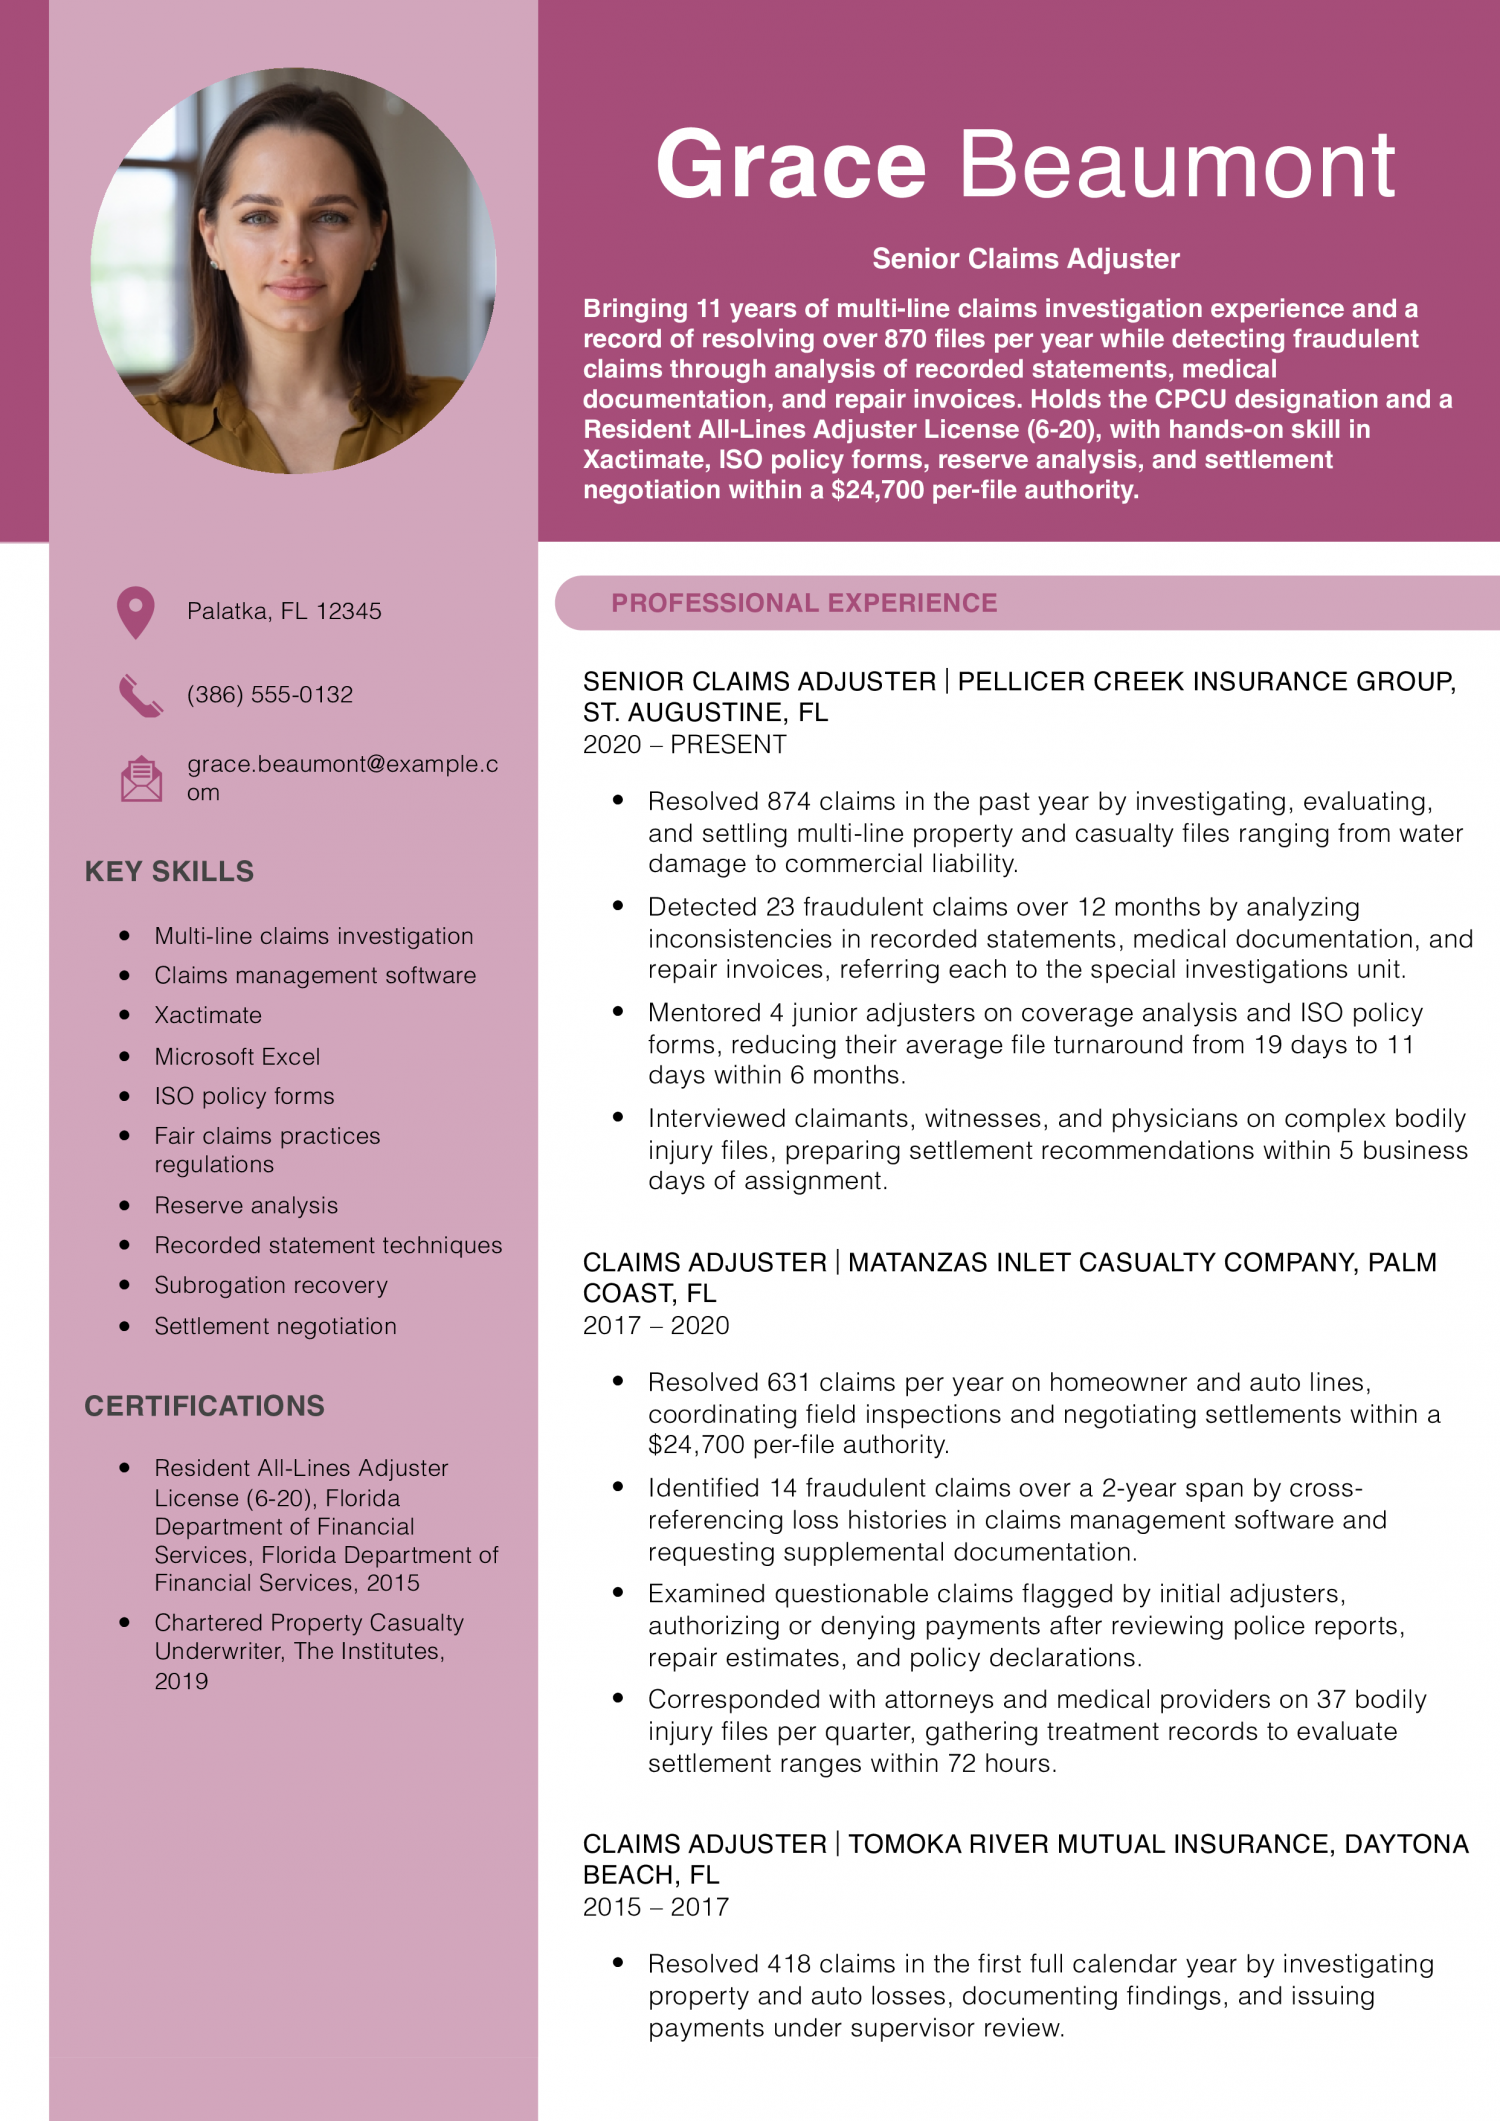
Lean on this resume if you are a senior claims adjuster with roughly a decade of property and casualty experience and a CPCU credential. Quantify fraud detection totals at each employer to show investigative instinct growing alongside your caseload.
Bodily injury analysis carries a clear delivery window here: settlement recommendations delivered within days of assignment. The deadline tells a claims manager when recommendations arrive. Name your own delivery window for analysis or reports so responsiveness is on the page, not left to the interview.
Dedicated to reducing documentation error rates across every role, most recently cutting claim file errors from 6.1% to 1.6% by standardizing note templates and verifying coverage declarations. Brings 6 years of experience managing up to 173 active residential property and personal auto claims, holding a Resident Adjuster License and working with Xactimate, claims management software, and ISO policy forms.
Open with your years of adjusting experience and the lines you handle. Name the claim types you work most often, such as auto physical damage and homeowner property.
Then name your typical coverage territory or region. Claims managers and insurance carrier recruiters scan this section in seconds. A profile that names your scope tells them whether your background fits the book they need covered.
State your average caseload size here too. If you handle field inspections, say so. If you work a desk queue, make that clear.
Strong adjuster resumes attach a number to each bullet. Start with your open caseload count per month. Include your average cycle time from first notice to closure.
Name the dollar range of reserves you managed.
If you reduced claim severity, state the percentage drop. Pair each metric with the action you took.
For example, write that you cut cycle time from 30 days to 22 by triaging new losses within four hours.
Sort your bullet points into the types of work you perform. Coverage analysis is one group. Include tasks like reading policy language and issuing reservation of rights letters.
Damage evaluation is another group.
List field inspections, photo documentation, and vendor estimates. Negotiation and settlement form a third category. Note recorded statements and subrogation recoveries there.
If you handle litigation files, add a group for coordinating with defense counsel. A fifth group could cover fraud detection, such as referring suspicious claims to your internal fraud team.
Create a credentials block near your profile section. If your state requires an adjuster license, list it with your state name and active status. Florida and Oklahoma are among the states that license staff adjusters.
Georgia registers staff adjusters through the employer instead.
Rules differ, so list the license where your state requires one. The Associate in Claims from The Institutes signals mid-career depth. The Chartered Property Casualty Underwriter signals senior expertise.
Name the claims platforms you use, such as Guidewire ClaimCenter or Xactimate.
Write your degree, school name, and graduation year. A bachelor’s degree in insurance, business, or finance is common in this field. If you hold an associate degree, list it the same way.
Below your degree, add any relevant coursework or training hours. If you are pursuing the AIC or CPCU designation, list it as in progress with your expected date. This closing section can also hold volunteer work or industry memberships.
Keep it brief, no more than five or six lines.
Five years ago, a Claims Adjuster resume read like a policy glossary. The mix has shifted toward data points and cycle time results. Software names now matter as much as coverage knowledge.
Claims managers and insurance carrier recruiters weigh hard skills first. They scan for tools and methods that cut claim cycle time. Soft skills like negotiation then confirm you can settle files on your own. Both types need to appear in your bullet points.
Compare each table with the job posting you plan to apply to. Pair each soft skill with a measurable result. Add a hard skill only when your work history backs it up. Leave out any term the posting skips. A tight list beats a long one every time.
| Soft Skills | AI-estimated % |
|---|---|
| Investigative judgment | 65% |
| Claimant communication | 63% |
| Detail orientation | 44% |
| Negotiation under pressure | 40% |
| Empathy with claimants | 29% |
And here are the top hard skills showing up most often.
| Hard Skills | AI-estimated % |
|---|---|
| Coverage determination | 72% |
| Liability assessment | 66% |
| Property damage estimation | 48% |
| Claims settlement processing | 37% |
| Medical record review | 33% |
Skill names and rankings come from an AI model grounded in U.S. Department of Labor occupation data for claims adjusters, not from a count of claims adjusters’ resumes built on ResumeTemplates.com.
Start with the keywords below.
Claims managers and insurance carrier recruiters scan for specific terms. Group your keywords by the type of claims you handle. Coverage analysis terms show you can read a policy. Investigation terms prove you verify facts before paying. Negotiation terms cover how you settle with claimants. Compliance terms signal you follow state rules and carrier guidelines. Credentials like AIC or CPCU belong in their own section. Each keyword category maps to a real adjuster task. Choose the terms that match your daily work. Then mirror those words in your bullet points.
Insurance carriers are split on AI in claims work. Some want adjusters who use AI tools to speed up estimates. Others worry about bias in automated decisions.
Name the tools you use on your resume. Describe how you check AI output before it reaches a claimant. Do not claim AI runs your workflow if you only use it for drafts.
Claims managers and insurance carrier recruiters want to see that you verify every AI result. Honest framing matters more than a long list of tools. Show what you do with the output, not what the model does alone.
What AI is actually changing for this role
Damage estimates: Computer vision tools scan photos and flag damage, but adjusters still confirm scope and pricing on site.
Fraud detection: Machine learning models score claims for fraud risk, and adjusters review flagged files before any denial.
Reserve setting: Predictive models suggest initial reserves based on claim features, though adjusters adjust them as facts change.
Document review: AI extracts data from police reports and medical records, reducing manual entry time per claim file.
Customer contact: Chatbots handle status updates and simple questions, freeing adjusters to focus on coverage and liability decisions.
AI tools to name
How to phrase AI on your resume
Do
Skip
Claims managers and insurance carrier recruiters look for credentials that prove you can handle loss files beyond a basic level. A state adjuster license is the starting point where your state requires one. Not every state does.
Florida and Oklahoma license staff adjusters, while Georgia registers them through the insurer instead. Beyond licensing, designations from The Institutes show deeper technical knowledge. They tell reviewers whether you can evaluate complex property losses or lead a high-severity claims team.
List the issuing body and your current status for each credential. Add the year you earned it so reviewers can gauge your experience level. Place these entries in a dedicated section near the top of your resume.
For Claims Adjusters, the 10th-percentile floor sits about 37 percent below the median. The top-decile ceiling runs roughly 50 percent above it. That gap is wide enough to reward line-of-business depth, geographic choice, and credential stacking over a career.
National employment is large, so the field absorbs new adjusters steadily. Still, where you land in the range depends on the claims you handle and the territory you cover. Position your resume around the claim types you have closed and the volume you carry.
Show your state adjuster license where your state requires one. Add the Associate in Claims or CPCU designation if you hold either.
| # | State | Median Annual |
|---|---|---|
| 1 | District of Columbia | $101,150 |
| 2 | New Jersey | $95,690 |
| 3 | Maryland | $95,560 |
| 4 | California | $91,790 |
| 5 | Connecticut | $88,330 |
| 6 | Alaska | $87,670 |
| 7 | New York | $87,130 |
| 8 | Rhode Island | $86,520 |
| 9 | Vermont | $83,970 |
| 10 | New Hampshire | $83,890 |
| # | State | Workers | Median |
|---|---|---|---|
| 1 | Texas | 29,220 | $78,800 |
| 2 | Florida | 28,100 | $76,920 |
| 3 | California | 24,290 | $91,790 |
| 4 | New York | 17,330 | $87,130 |
| 5 | Illinois | 14,210 | $77,010 |
Resume Templates offers HR approved resume templates to help you create a professional resume in minutes. Choose from several template options and even pre-populate a resume from your profile.
Apply for trainee roles at insurance carriers. A business or finance degree can help, but a high school diploma or equivalent is typically sufficient for entry-level claims adjuster roles. Highlight transferable skills such as investigation, negotiation, and customer service from prior jobs.
In states like Florida or Oklahoma, you will also need to obtain the required adjuster license before you begin.
Yes. Claims adjuster experience signals strong analytical and negotiation skills that transfer well into risk management or underwriting roles. Quantify your results with settlement volumes or claim closure rates so the experience carries measurable weight.
Pull keywords from the job posting first. Common terms include liability determination, subrogation, and reserve setting. Also list the claims software you have used, such as Xactimate or Guidewire ClaimCenter.
These terms help your resume pass through applicant tracking systems before a recruiter reads it.
A property adjuster resume should stress roof inspections, structural estimates, and tools like Xactimate. An auto adjuster resume should focus on vehicle appraisals and total loss valuations.
Tailor every bullet to the claim type the posting describes so claims managers see an exact match.
Yes, if your state requires one. Florida and Oklahoma both require licensed adjusters, so listing your active license shows you meet a legal prerequisite. In Georgia, staff adjusters are registered by their employer, so note that registration status instead.
Place the license or registration near the top of the first page for quick review.
Note any relevant activity during the gap, such as coursework or earning the Associate in Claims designation. If the gap was personal, a one-line note is enough.
Focus the rest of the resume on measurable claim outcomes so the gap does not dominate the page.
A second page is reasonable if you have more than 10 years of experience across multiple carriers or claim types. Keep the strongest results and most recent roles on the first page.
Claims managers often scan page one in under 30 seconds, so front-load your best numbers there.
Try an ATS-friendly template that keeps your certifications and work history in their own sections. A basic template works well for this too.
Claims Adjuster Resume
4.1/5 stars with 191 reviews

Executive Resume Writer and Career Coach
Andrew Stoner is an executive career coach and resume writer with 17 years of experience as a hiring manager and operations leader at two Fortune 500 Financial Services companies, and as the career services director at two major university business schools.
© 2026 Resumetemplates.com All rights reserved.